
LAGOS, Nigeria – Nigeria is preparing to sign a digital trade agreement with five African countries in a move aimed at helping financial technology companies and digital businesses expand across the continent. The proposed arrangement brings together Nigeria, Ghana, Kenya, Rwanda, South Africa and Egypt as governments seek to remove regulatory barriers that continue to restrict cross-border business.
Nigeria’s Minister of Industry, Trade and Investment, Jumoke Oduwole, announced the initiative on 16 November 2026. The six countries expect to sign the agreement during an African Continental Free Trade Area (AfCFTA) Council of Ministers meeting in Zimbabwe before the end of November.
The proposed deal could create new opportunities for African fintech companies, digital payment providers and technology businesses seeking access to regional markets. It also represents an effort to translate the AfCFTA’s ambitions into practical measures that support trade in services and regional investment.
Oduwole said Nigeria identified the five partner countries after examining where its technology-enabled businesses wanted to expand. The government then brought together regulators, including central banks and trade ministries, to explore ways of improving cooperation between the participating markets.
The initiative responds to a persistent challenge facing African technology companies. A business operating successfully in one country often encounters different licensing requirements, financial regulations and compliance procedures when entering another market. These differences increase costs and can delay regional expansion.
Nigeria hopes closer regulatory cooperation will make it easier for businesses to reach customers beyond their domestic markets. However, the participating governments have not disclosed the agreement’s final terms or confirmed whether it will immediately change licensing, taxation, capital requirements or other market-entry rules.
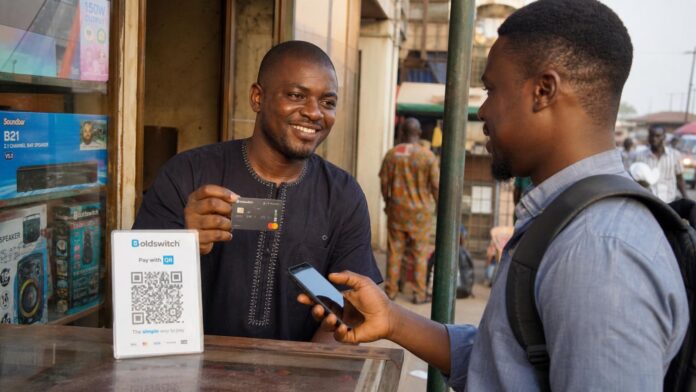
The proposed agreement could be particularly significant for Nigeria’s fintech industry, which has emerged as an important source of digital financial innovation in Africa. Nigerian companies have developed payment platforms, digital banking services and technology solutions serving consumers and businesses across different markets.
Despite this growth, cross-border expansion remains complicated. Financial service providers must navigate national banking regulations, payment infrastructure requirements and consumer protection rules. These obligations can limit the speed at which businesses launch services in neighbouring countries.
Greater cooperation between regulators could help reduce some of these difficulties. Clearer procedures and improved coordination may allow companies to expand more efficiently while maintaining compliance with national laws.
The six participating countries represent some of Africa’s most important economic and technology markets. Nigeria brings a large consumer population and an established fintech industry, while South Africa offers a developed financial services sector and significant institutional investment capacity.
Kenya has built a strong reputation for mobile money and digital payments. Rwanda continues to promote technology-led economic development, while Ghana has expanded its digital financial services sector. Egypt provides access to a major North African market with growing technology and financial services industries.
Closer cooperation among these economies could strengthen commercial connections between West, East, Southern and North Africa. It may also encourage companies to develop products that serve customers across several countries rather than operating within separate national markets.
The agreement forms part of Nigeria’s wider strategy to use the AfCFTA to expand opportunities for domestic businesses. The continental trade framework aims to strengthen economic integration by reducing barriers to trade and creating a more connected African market.
Although the AfCFTA has established a foundation for regional trade, businesses still face challenges when moving goods, services and capital across borders. Differences in regulations, infrastructure limitations and administrative procedures continue to restrict commercial activity.
Digital trade presents an opportunity to address some of these obstacles. Software companies, online service providers and financial technology businesses can reach customers beyond their home markets without relying entirely on traditional physical distribution networks.
However, digital businesses still require reliable payment systems, data protection arrangements and legal certainty. Without these conditions, companies may struggle to operate effectively across multiple jurisdictions.
The proposed six-country initiative could help participating governments identify practical solutions to these challenges. Regulatory cooperation may also improve communication between financial authorities and reduce uncertainty for businesses planning regional investments.
The development comes as Africa’s digital economy continues to expand. According to the GSMA’s Mobile Economy Africa 2026 report, mobile technologies and services contributed approximately US$240 billion to the continent’s economy in 2025, equivalent to 7.8% of regional GDP.
The industry also supported approximately 13 million jobs, demonstrating the growing importance of mobile connectivity and digital services to economic activity. GSMA projections indicate that the sector’s contribution could reach US$290 billion by 2030.
These figures highlight the potential economic value of improving digital market access. As more African businesses adopt mobile payments, e-commerce and online services, the demand for efficient cross-border transactions is likely to increase.
Nevertheless, market access alone will not guarantee success. Technology companies will still need to meet regulatory standards, protect customer information and provide reliable services in each country where they operate.
Financial inclusion also remains an important consideration. Many consumers and small businesses continue to face barriers involving internet affordability, digital skills and access to formal financial services.
A more connected digital market could support financial inclusion if companies use regional expansion to introduce affordable payment products and accessible financial services. Small enterprises may also benefit from easier access to regional customers and suppliers.
Nigeria is pursuing additional trade reforms alongside the proposed agreement. The government plans to launch the second phase of its National Single Window project on 14 December 2026, introducing further digital processing of export permits and documentation.
The platform aims to simplify administrative procedures by allowing exporters to submit documents and obtain approvals through a centralised digital system. More efficient processing could reduce delays and improve the operating environment for businesses involved in international trade.
Together, the digital trade initiative and export reforms reflect Nigeria’s efforts to strengthen its commercial links with other African economies. They also demonstrate the growing importance of technology in the continent’s trade and investment strategies.
Oduwole has encouraged Nigerian development finance institutions to support more business activity across Africa. The government is also assisting companies with requirements involving product standards, rules of origin and access to export markets.
These measures could help Nigerian businesses compete more effectively while creating opportunities for partnerships with companies in other African countries.
The broader challenge will be turning political commitments into changes that businesses can measure. Companies will need clarity on the agreement’s regulatory provisions, implementation timetable and procedures for entering participating markets.
A successful arrangement could provide a model for wider cooperation under the AfCFTA. Other African countries may eventually explore similar approaches if the six participating governments demonstrate that coordinated regulations can reduce barriers to digital trade.
However, the agreement has not yet been signed, and its potential benefits remain dependent on negotiations and implementation. Businesses should therefore not assume that existing licensing or regulatory restrictions have already changed.
Nigeria’s initiative represents an important step towards a more connected African digital economy. Its long-term significance will depend on whether participating countries can convert the proposed agreement into practical opportunities for fintech companies, digital entrepreneurs and businesses seeking to expand beyond national borders.
As African economies seek new sources of investment and growth, stronger digital trade cooperation could help create a regional market capable of supporting innovation, competition and greater economic participation.