
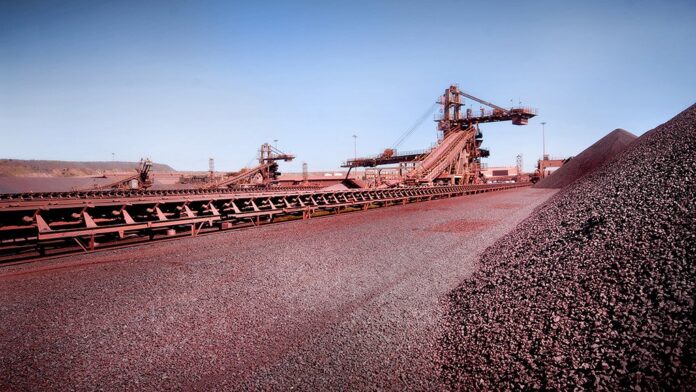
Johannesburg, 12 November 2026. South Africa mining output fell 10.7% year on year in September, Statistics South Africa reported. Mineral sales dropped 4.1% over the same period. The figures extend a weak run for a sector that remains central to the country’s economy and exports.
Production fell by more than a tenth compared with September 2025. Sales fell by less than output, although the two measures are not directly comparable. Both moved the wrong way. Stats SA released the data on Thursday morning, and markets had been waiting for it.
Analysts had forecast another contraction. In August, mining output fell 12.7% year on year. Nedbank economists said they expected the weakness to continue into September. They pointed to high input costs, made worse by steep fuel prices, and to structural constraints that weigh on the sector.
In other words, the September number surprised few people. The question is how long the pressure lasts.
The rand softened in early trade before the release. At 0529 GMT it traded at 16.62 against the dollar, down 0.2% from its previous close. Reuters linked the move to a stronger dollar. Investors also raised their bets on further US Federal Reserve rate rises after stronger-than-expected October inflation data. Some officials left open the chance of a larger 50-basis-point increase.
South Africa’s benchmark 2035 government bond was steady, with a yield of 8.465%. Therefore, the data arrived at a time when currency and bond markets were already sensitive to global interest rates.
Two months of double-digit declines point to cost pressure more than to a lack of resources. The figures are year-on-year comparisons, so the level of output a year earlier also plays a part. The full Stats SA release breaks the data down by commodity, and editors should consult it before drawing conclusions about individual minerals such as gold or platinum.
Higher fuel and input costs affect mines of every size. Meanwhile, a weaker rand can help exporters, but it also raises the cost of imported equipment and fuel. These forces pull in different directions, and the net effect varies by producer.
Three things will shape the next few months. First, the October production figures will show whether the decline is easing. Second, fuel prices and input costs will decide how profitable mining stays. Third, US interest rate decisions will influence the rand and global demand for metals.
Mining analysts will also watch any government and industry steps to cut costs or ease constraints.
How much did output fall in September? 10.7% year on year, according to Statistics South Africa.
What happened to mineral sales? They fell 4.1% year on year.
What was the August figure? Output fell 12.7% year on year in August.
What do economists blame? Nedbank cites high input costs, steep fuel prices and structural constraints.
How did the rand react? It softened to 16.62 per dollar in early trade, down 0.2%.
Mining is a major employer and a leading source of export earnings for South Africa. A weak run therefore affects jobs, public revenue and the wider economy. For that reason, analysts watch these monthly releases closely. Investors also compare the data with trends in other African producers, since many of the continent’s resource economies face similar cost pressures.
Costs, not geology, are the main worry for South African miners right now. The sector still has strong resources, and a fall in costs could help it recover. Fence Africa 24 will report the October figures when they are published.